Earnest Money Deposit Explained: A Complete Guide for Real Estate Buyers
Given the importance of earnest money deposits in today’s CRE market, it’s safe to say that slow and steady certainly does not win the race. Rather, the winning investor is invariably the one who can move as quickly as possible to meet the seller’s earnest money deposit (EMD) requirements with ease.
That deposit is more than a formality. It can tie up hundreds of thousands or even millions of dollars, signal that a buyer is serious, and determine whether a transaction moves ahead as planned. Miss the deadline, misunderstand the terms, or fail to fund it, and a deal that took months to negotiate can suddenly be at risk.
So, what exactly is an earnest money deposit (also known as a good faith deposit), how much do CRE buyers typically need, and what happens to the money after it changes hands?
This guide breaks down everything buyers need to know about earnest money deposits in commercial real estate: from how much to pay and when it’s due to how EMDs are funded, when they can be refunded, and what can happen when a buyer fails to deposit the required funds.
We’ll cover the following:
- What is an Earnest Money Deposit? An introduction
- How EMDs work in commercial real estate
- EMD lending: How to secure EMDs for all deals
Do you want to build your CRE portfolio without worrying about EMDs? Contact us now to learn more about how our EMD financing solution can help your business.
Fund your next real estate deal
- Access fast financing
- Grow your real estate portfolio

1. What is an Earnest Money Deposit? An introduction
An earnest money deposit (EMD) in real estate is a percentage of the purchase or sale price of a property that the seller demands as a signal of the buyer’s willingness and readiness to close the deal.
EMDs have become an important part of every real estate transaction, as sellers seek to quickly close deals rather than waste time on prospects who are not ready to get the deal done.
“Earnest money deposits are part of every deal; they are part of every transaction,” says Stash Geleszinski, a managing director at Capstone, the largest privately held multifamily investment sale firm in the US.
Interestingly, buyers have also expanded the meaning of EMD to make it a useful negotiation tool in competitive markets. For example, if the seller demands 5% of the purchase price as an EMD, a buyer who wants to stand out can propose paying 10% to stand above the fray.
What does paying an EMD confer on the potential buyer?
When a potential buyer pays an EMD, the seller takes the property off the market for a stated period. This period is known as the due diligence period and can last between 20 and 90 days, depending on the CRE type.
During this period, the buyer conducts a deep investigation into the property, primarily to confirm if it meets their financial, physical, and legal expectations. It often involves a title search, zoning compliance confirmation, physical assessments, lease verification, among others.
The results of this due diligence will determine if the potential buyer goes on to close the deal or not. During this period, the potential buyer can walk away from the transaction for any reason without incurring any penalty.
However, walking away after the period expires comes with a cost. But more on that later.
What are the differences between EMDs and due diligence fees/option fees?
EMDs are sometimes confused with due diligence fees or option fees. Clarifying the distinction will help us better understand what EMDs are all about.
In some residential markets, the payment of an EMD is not enough for the seller to take the property off the market and grant the buyer the right to walk away for any reason during the due diligence period. To get these rights, they need to pay an extra fee: a due diligence fee (in North Carolina and South Carolina) or an option fee (in Texas).
Fortunately, this distinction between earnest money deposit and due dilligence fees is irrelevant in CRE since the payment of the former confers on potential buyers the rights that only the latter does in certain residential markets.
What are the differences between EMDs and down payments?
The down payment is a portion of the property’s purchase price that the buyer must provide to secure a mortgage loan for the rest of the amount. Many financing companies request between 20 and 40% down payment before they can provide debt financing, with higher down payment often resulting in lower interest rates.
Below are the main differences between an earnest money deposit and a down payment:
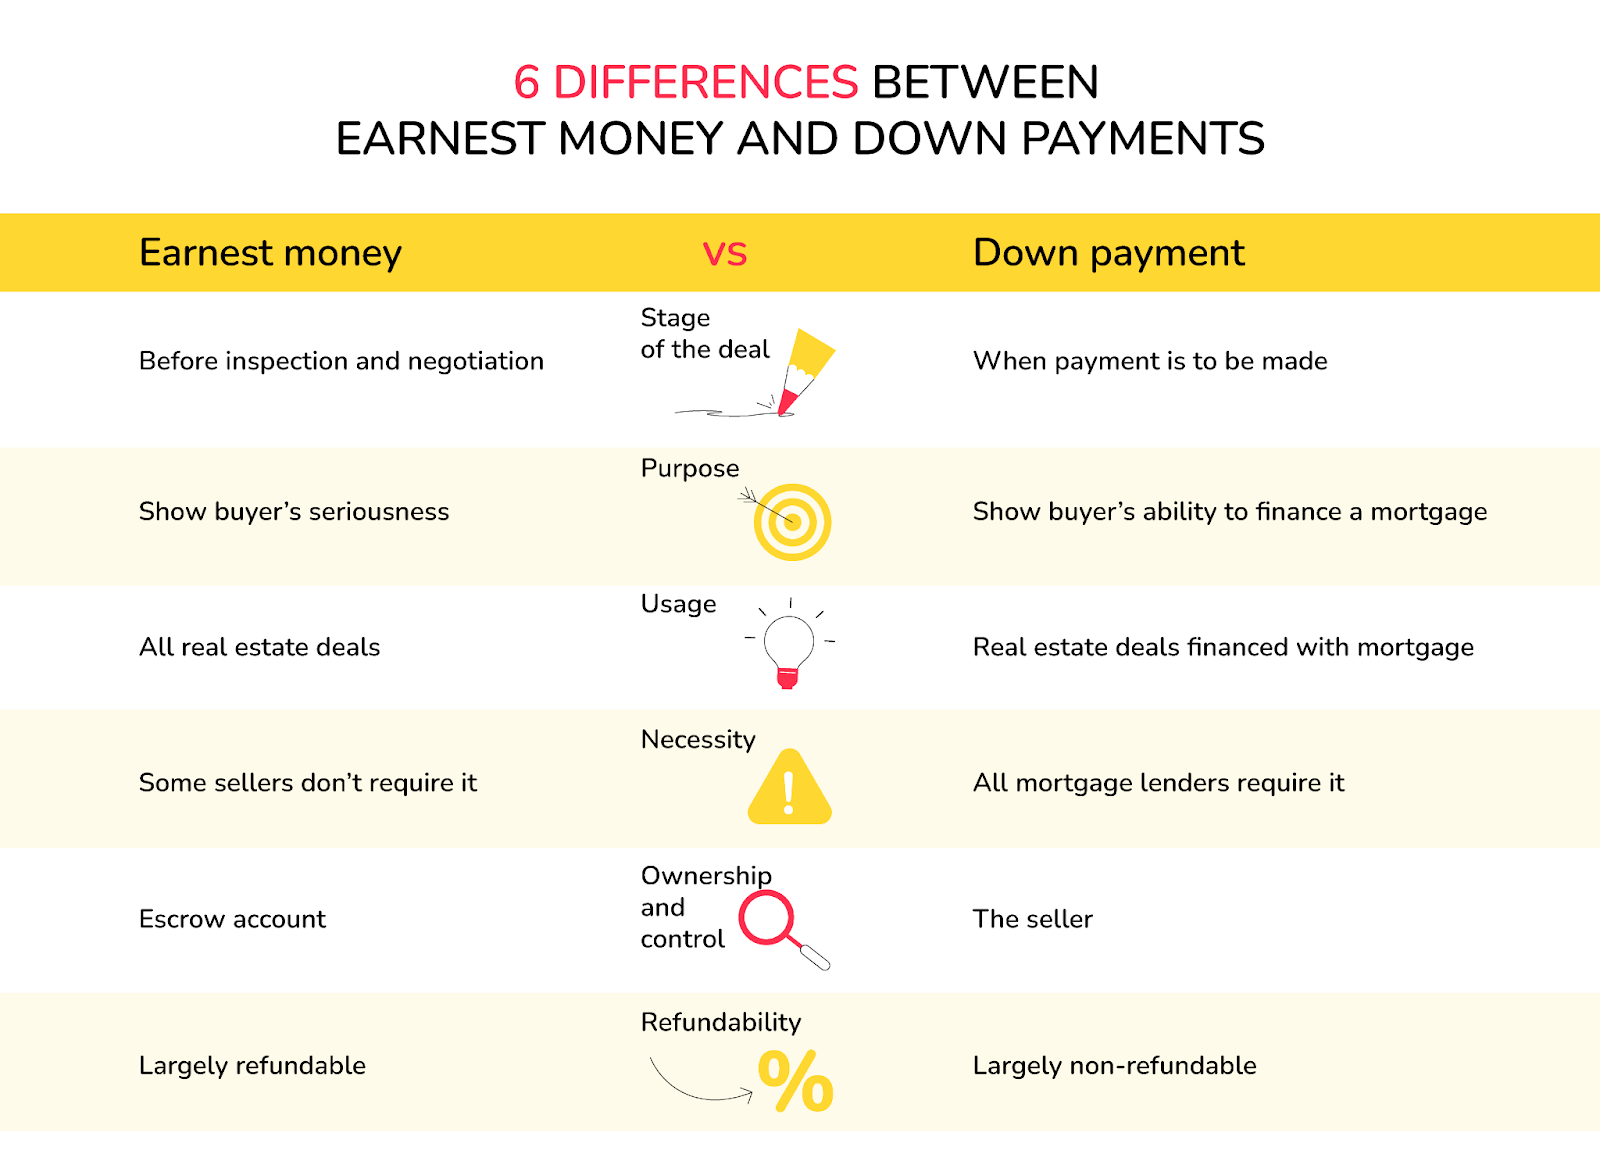
The key point here is that EMDs are paid before the due diligence period kicks off, while the down payment is made when a deal has been agreed upon after the due diligence period.
“An EMD gets you to the table and buys you due diligence time, but the down payment is what actually transfers ownership,” according to Brett Sherman, a real estate broker at Signature Realty, a CRE agency in Miami. “Think of EMD as your entry fee and the down payment as your actual bet.”
2. How EMDs work in commercial real estate
Now that we have clarified what EMDs are, let’s consider how they work in CRE:
How much earnest money deposit is typically required?
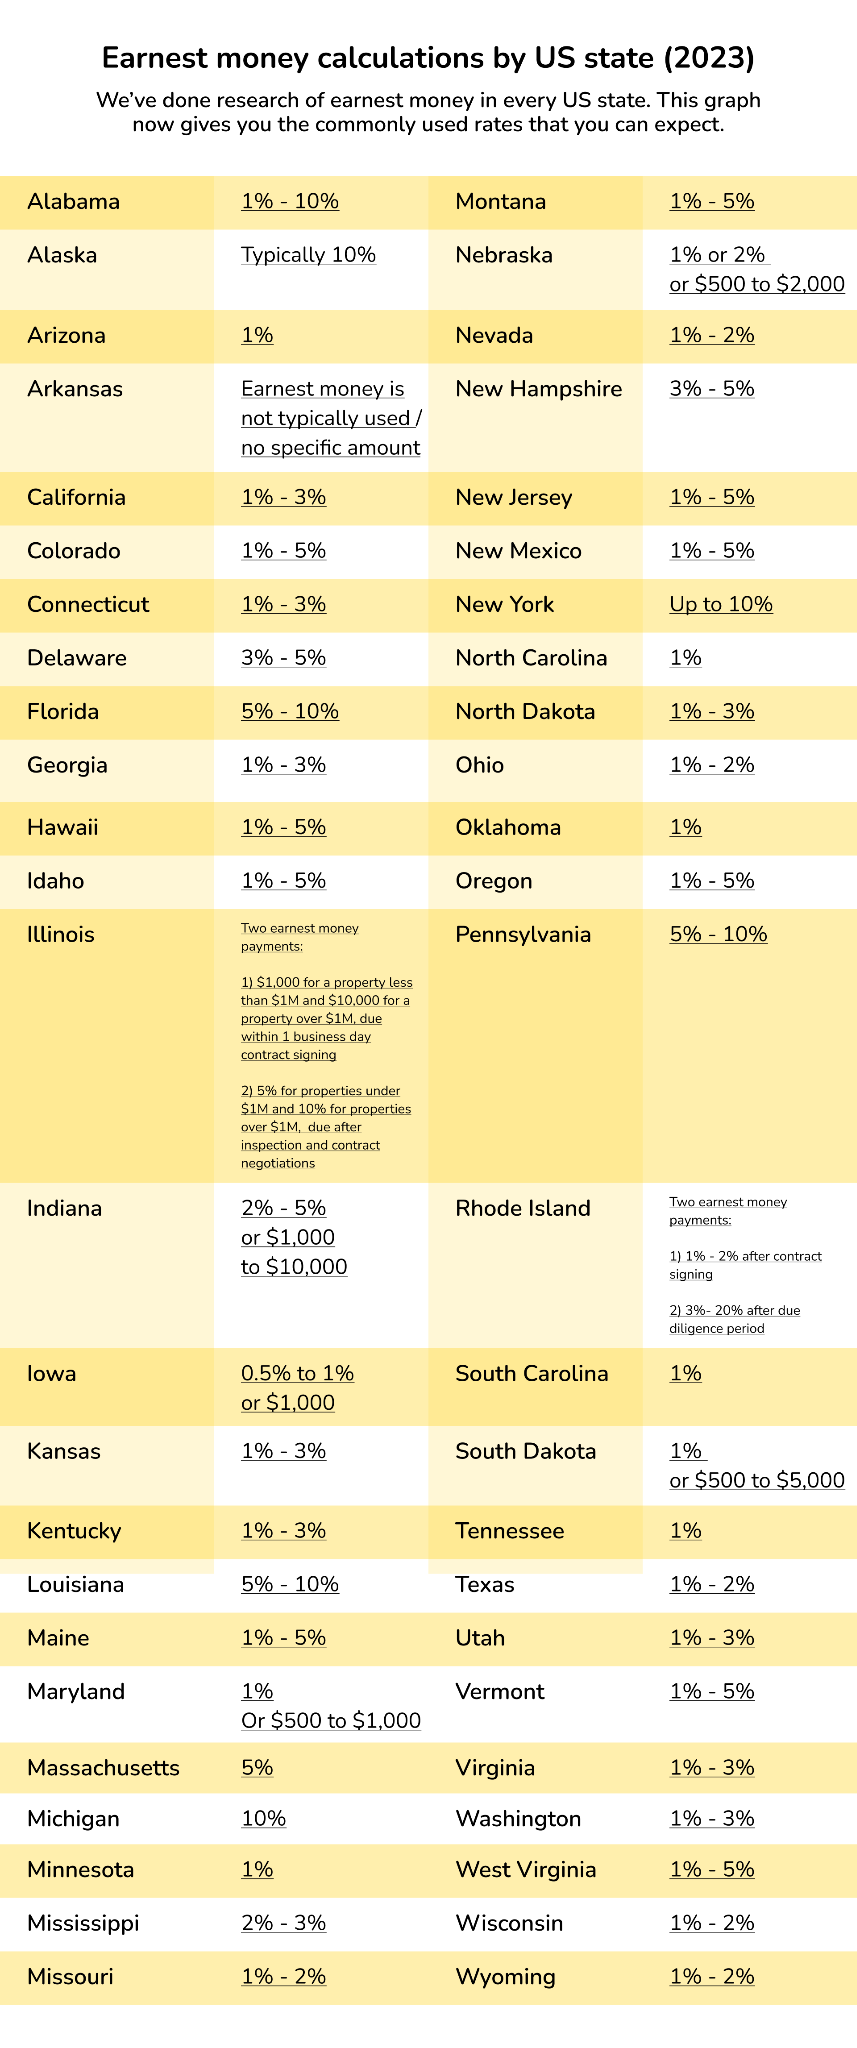
EMD requirements differ among US states, but the average range is between 3% and 10% for commercial properties.
But how much is earnest money for commercial property in each US state?
Below is the typical range, based on our comprehensive survey:
When is earnest money due?
In commercial real estate, the EMD is usually due one to three days after the execution of the Purchase and Sale Agreement (PSA), also known as the purchase contract (from the buyer’s perspective) or sales contract (from the seller’s).
Most importantly, the payment deadline is written into the contract itself, which gives room for negotiation between the buyer and the seller.
Where does earnest money deposit go?
Earnest money is paid to an escrow agent who holds the money on behalf of both parties. An escrow agent can be a title company, a real estate agent, a real estate broker, a real estate attorney, or a dedicated escrow company.
Both parties agree to the selected escrow, and this will be included in the PSA.
How do you pay earnest money?
EMD can be paid to the escrow account through cashier’s check, certified check, personal check, and wire transfers.
Wire transfers are the most popular for CRE transactions. Cashier’s checks, certified checks, and cash are rare in institutional CRE deals.
The escrow agent typically issues a receipt once the funds clear. This proof of payment is shared with the buyer to confirm compliance with the PSA.
What is earnest money used for?
When the deal succeeds and gets to closing, EMD can be used to offset some of the closing costs of the transaction. Alternatively, it can be added to the down payment for the property itself.
If the deal does not succeed, the earnest money may be refunded to the potential buyer or sent to the seller. More on this below.
What happens if a buyer does not deposit earnest money?
What happens if a buyer does not deposit earnest money depends on the details agreed in the PSA.
If the PSA clearly states that the payment of an EMD is a requirement and that there is a given deadline for it, then an automatic breach of contract has occurred when the potential buyer does not deposit the earnest money.
When an automatic breach has happened, the buyer loses purchase rights, and the seller is free to put the property back on the market.
If the PSA does not contain an automatic-void clause, the contract remains legally binding. Consequently, it can only be terminated by a mutual agreement between the seller and the buyer. Only when they have come to this agreement can the seller accept a new offer.
Is an EMD refundable? Overview of refundability rules
This is one of the popular questions regarding how EMDs operate.
The simple answer is that EMDs can be refundable or non-refundable, depending on the scenario.
A look at the earnest money refundability conditions in CRE will bring much clarity to this topic.
3. EMD lending: How to secure EMDs for all deals
As we saw above, the competitive nature of most CRE markets means non-payment or delayed payment can easily lead to an automatic breach of contract, which gives the seller the right to cancel the deal and relist the property.
In other words, quickly coming up with earnest money is not a luxury in CRE.
“Given the access to multiple properties thanks to digital listings platforms, CRE investors now have a variety of options for potential acquisitions,” according to Anna Kogan, the CEO of Duckfund.
However, “while it is critical to have access to multiple deals at once to choose the most lucrative one, it is also important to move very quickly in a competitive market.” This is because “If there are several bidders for the deal, the first to come up with the deposit eventually wins the deal.”
When investors are illiquid or have other uses for the cash they have, they resort to earnest money deposit financing, of which EMD lending is the most accessible, flexible, scalable, and cost-effective.
EMD lending is a form of gap funding or bridge capital for earnest money. It provides short-term bridge financing to cover the EMD while investors arrange permanent funding for the full purchase price. With this, buyers can secure contracts quickly and repay the EMD loan once long-term financing is in place.
These loans are provided by specialized earnest money deposit providers like Duckfund.
Specialized EMD lending is accessible, with many providers focusing on the quality of the deal rather than credit reports or credit scores. Also, these providers make funding available within 48-72 hours, aligning their services with the competitive nature of the CRE market.
Furthermore, EMD loans are scalable, since many providers finance multiple simultaneous deals.
Accessing EMD lending with Duckfund
Duckfund seeks to help you build profitable CRE portfolios without being held back by EMD requirements.
With us, you can complete an application within five minutes. We don’t request credit reports or credit scores; instead, we require an executed PSA, since our primary focus is on the details of the deal itself.
Once approved (within 24 hours), we send the money to the listed escrow agent within 48 hours.
For investors operating in very competitive markets, we offer the option to propose higher EMD amounts to gain an advantage.
Furthermore, we support multiple simultaneous deals so you can pursue different deals at the same time without being held back by EMD requirements.
More than financing some CRE deals here and there, we hope to be your financing partner as you grow your portfolio.
Are you ready to secure EMD financing for your CRE deals? Sign up now with Duckfund for quick, cost-effective, and flexible access to EMD loans.
Takeaways
- An earnest money deposit shows a CRE buyer’s commitment to a transaction and gives the buyer time to complete due diligence before closing.
- Commercial real estate EMDs typically range from 3% to 10% of the purchase price, with the exact amount and payment deadline determined by the purchase and sale agreement.
- EMDs can be refundable or non-refundable, depending largely on whether the buyer exits during the due diligence period and what the PSA says about the deposit.
- Missing an EMD deadline can put the entire transaction at risk, while EMD financing can help buyers preserve liquidity and move quickly when capital is tied up elsewhere.
Frequently Asked Questions
1. What does EMD stand for in real estate?
EMD stands for Earnest Money Deposit. It is a sum of money a buyer deposits to demonstrate their commitment to purchasing a property and secure time to complete due diligence before closing.
2. Can an earnest money deposit be negotiated?
Yes. The EMD amount and other deposit terms are generally negotiated between the buyer and seller and documented in the purchase and sale agreement. In competitive CRE markets, a buyer may even offer a larger deposit to make an offer more attractive.
3. Who holds the earnest money deposit during a CRE transaction?
An escrow agent typically holds the EMD on behalf of the buyer and seller until the transaction reaches a point where the funds can be released. The escrow agent may be a title company, real estate broker, or dedicated escrow company, depending on the transaction and the terms of the PSA.
4. Does an EMD earn interest while it is held in escrow?
Not necessarily. Whether an EMD earns interest depends on the escrow arrangement and the terms agreed upon by the parties. Buyers should review the PSA and escrow instructions to determine whether the funds will be held in an interest-bearing account and who receives any interest.
5. Can a buyer use the EMD toward the purchase price at closing?
Yes. When the transaction closes, the EMD can generally be credited toward the buyer’s purchase obligations, such as the down payment or certain closing costs, depending on the terms of the transaction.
6. What happens to the EMD if the seller backs out of the deal?
The treatment of the deposit depends on the purchase agreement and the reason the transaction fails. If the seller breaches the agreement under circumstances that entitle the buyer to terminate, the EMD may be returned to the buyer.
7. Can a buyer use the same EMD funds for multiple properties?
Generally, no. Once an EMD is deposited into escrow for a transaction, those funds are committed to that specific deal until they are released. Buyers pursuing multiple acquisitions may therefore need additional liquidity or separate financing for each transaction.
8. Why do CRE buyers sometimes prefer to finance an EMD instead of using cash?
Financing an EMD can allow buyers to preserve cash for other transaction expenses, acquisitions, renovations, or working capital instead of tying it up in escrow. This can be particularly useful when a sponsor is pursuing multiple opportunities simultaneously.
9. What should buyers check before sending an EMD?
Before funding an EMD, buyers should review the PSA for the deposit amount, payment deadline, escrow instructions, release conditions, and consequences of failing to fund on time. Confirming the escrow details and wiring instructions with the appropriate parties can also help prevent costly payment errors.
Real Estate
Financing

- Approval within 24 hours
- Fund multiple properties at once
- No full deposit upfront — soft deposit only
- Apply in under 2 minutes
Secure your next commercial property acquisition — zero upfront capital required.
Start with Duckfund’s EMD financing program.- No capital commitment
- Close faster
- Scale with confidence
